In as we speak's financial landscape, monetary difficulties can strike anybody at any time. For people with poor credit score histories, accessing traditional types of credit can pose vital challenges. This has given rise to a distinct segment marketplace for guaranteed bad credit payday loans, a monetary product that promises to offer quick relief to these in dire need. This observational research article seeks to investigate the implications, processes, and consequences related to these loans by inspecting borrower experiences, lender practices, and the wider societal impacts of this financing option.
Payday loans are brief-time period, excessive-interest loans sometimes used to cover unexpected bills or to bridge a hole till the subsequent payday. For those with bad credit score, typical options such as personal loans from banks or credit unions could be off the desk, main them to contemplate payday lending companies. Though many payday lending companies promote guaranteed approval regardless of credit score historical past, the terms associated with these loans typically reveal a more advanced narrative deserving of scrutiny.
The Borrower Expertise
Interviews with borrowers recommend that those who pursue guaranteed bad credit payday loans typically view them as a final resort. Common themes emerge from these conversations: urgency, desperation, and an absence of financial literacy. Many borrowers expressed feeling trapped by circumstances such as medical emergencies, automotive repairs, or sudden job loss, which left them with limited options for obtaining funds.
One subject, a middle-aged single guardian named Lisa, described her experience with a payday loan as "a needed evil." After dropping her job, she needed to cowl essential bills. Regardless of her reluctance, she turned to a payday lender because of advertising that highlighted their assured approval, regardless of financial historical past. Lisa noted, "I felt like I had no selection. They stated I can be accepted instantly." Though she was approved quickly, the aftermath proved difficult: she struggled with high curiosity charges that sophisticated her repayment course of.
Lender Techniques and Practices
Guaranteed bad credit payday loans are sometimes marketed aggressively, capitalizing on the desperation of people in financial distress. Lenders frequently utilize various ways to draw borrowers, together with simplified software processes and deceptive advertising. Many of those loans additionally come with hidden charges and obligations that borrowers could not absolutely comprehend on the time of agreement.
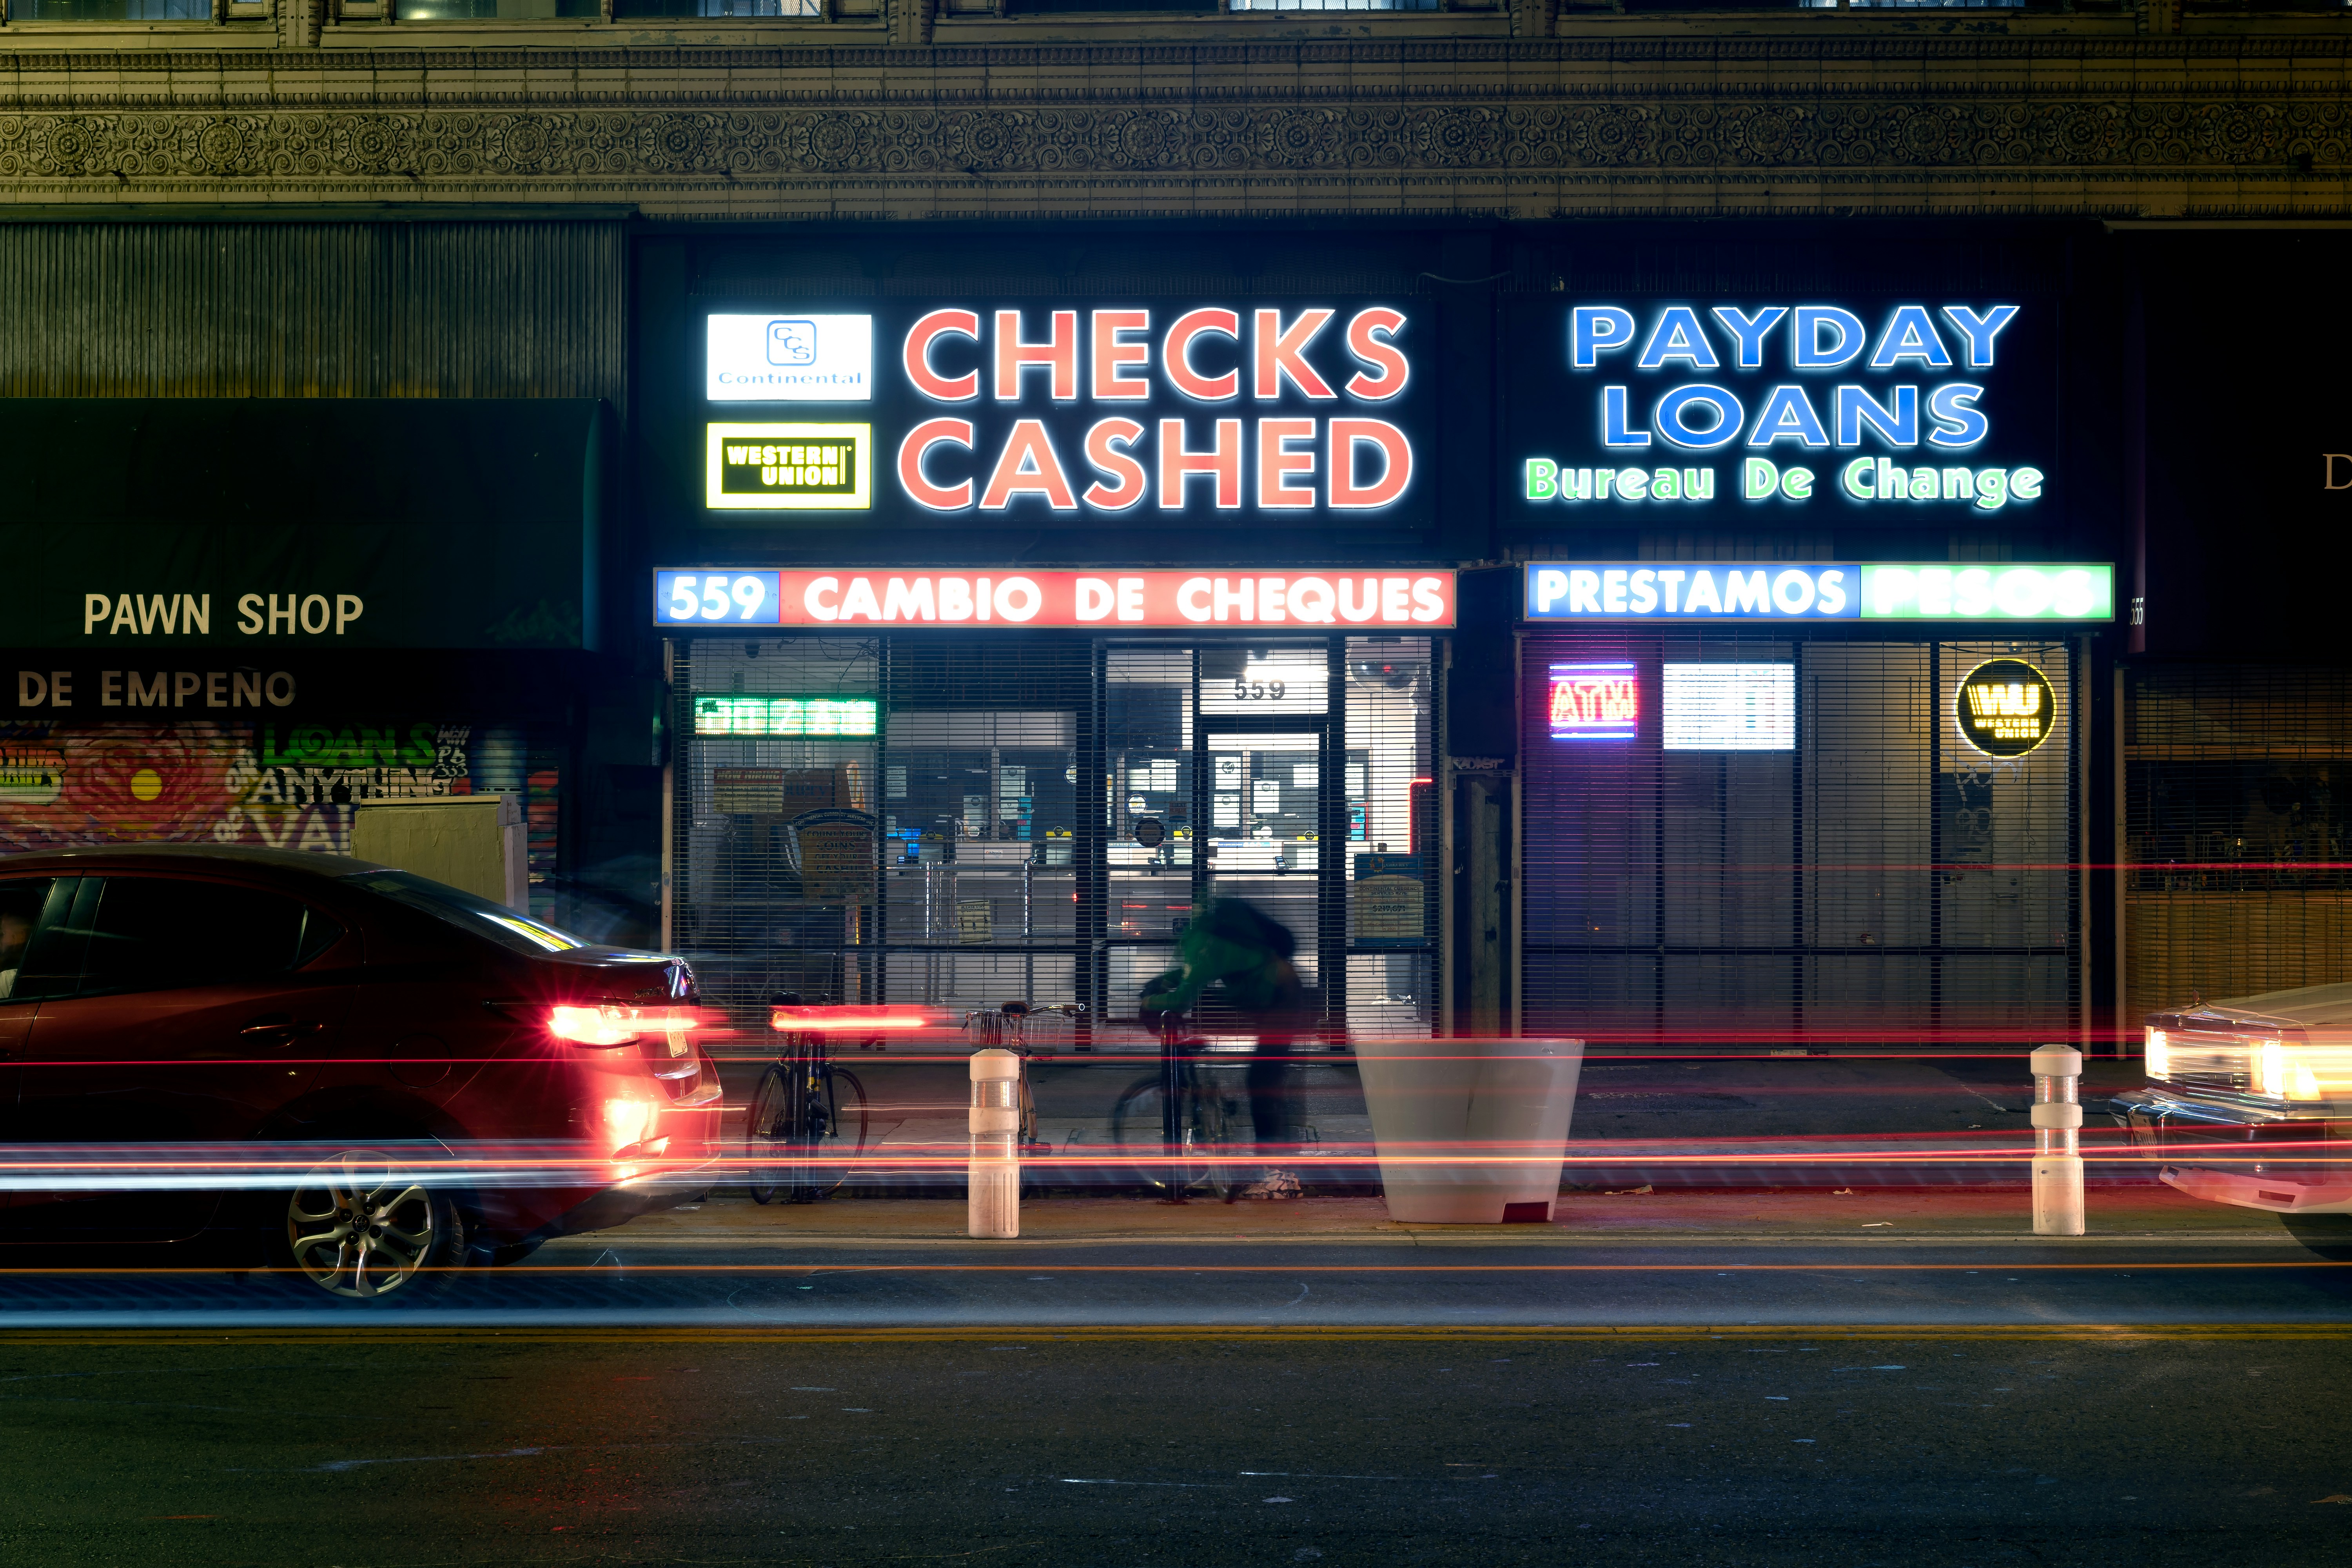
From field observations of native payday lending establishments, it is obvious that lenders function in a grey space of ethics. Many stakeholders do not conduct thorough assessments of a borrower's potential to repay; as a substitute, they rely predominantly on the borrower's expression of need. Throughout interviews with lending representatives, it turned obvious that they're educated to emphasise the speed and accessibility of loan funds while downplaying the lengthy-time period implications of excessive-interest charges. One consultant mentioned, "We’re offering them a lifeline," however didn't tackle how that lifeline might depart borrowers with crippling debt cycles.
The Debt Cycle
A significant concern concerning guaranteed bad credit payday loans is the potential for borrowers to enter a cycle of debt. Most payday loans are due inside a short timeframe, sometimes two weeks, coinciding with the borrower's next paycheck. Nevertheless, many borrowers struggle to repay the preliminary loan because of the exorbitant curiosity rates – typically averaging upwards of 400% APR. Consequently, borrowers generally resort to taking out new loans to repay current debts, creating a perpetual loop of borrowing.
Observational information indicated that some people resorted to borrowing from multiple lenders to handle their monetary obligations. This multi-lending apply can stretch personal sources skinny, usually resulting in a downward spiral of financial instability. For example, one borrower named John candidly expressed, "I took out three loans simply to pay the final one. At this level, I feel like I’m simply chasing my tail." This cycle not solely strains individuals but additionally influences neighborhood relationships and overall economic nicely-being.
Societal Implications
The implications of guaranteed bad credit payday loans prolong beyond individual borrowers; they affect communities and the economic system at massive. When individuals are trapped in cycles of debt, their buying power diminishes. Observational analysis in low-income neighborhoods indicated a concerning pattern – elevated reliance on payday loans correlates with decreased spending on local companies and items.
Moreover, this reliance on excessive-interest loans can breed social instability. Borrowers may expertise heightened stress, anxiety, and decreased total effectively-being, affecting their interactions with household, jobs, and neighborhood. The contribution of payday loans to the systematic impoverishment of weak populations remains a urgent issue that warrants additional examination.
Regulatory Measures and Future Directions
As research continues to shed mild on the challenges posed by guaranteed bad credit payday loans, there's a rising consensus that complete regulatory measures are mandatory. Advocates call for stricter controls on curiosity rates, transparency in lending practices, and improved financial literacy initiatives to equip potential borrowers with needed knowledge.
In recent years, some states have taken steps to regulate payday lending practices with better shopper protections. These efforts have led to a decrease in lending abuse in sure areas, however the variability of legal guidelines makes it crucial for continued advocacy at both native and nationwide levels. Elevated consciousness and training about the dangers involved in payday loans are important for empowering potential borrowers to make informed decisions.
Conclusion
Guaranteed bad credit payday loans represent a fancy and often troubling side of modern finance. Whereas they provide fast cash relief for people in rapid want, the long-time period implications of those loans on financial stability and neighborhood well being are important. Observing borrower experiences reveals a cycle of desperation and monetary mismanagement that perpetuates socioeconomic challenges. As society moves ahead, it turns into increasingly necessary to advocate for more constructive monetary solutions that empower individuals somewhat than entrap them in debt cycles. Within the face of economic adversity, knowledgeable decisions and protecting regulations stay important to fostering a healthier financial ecosystem.