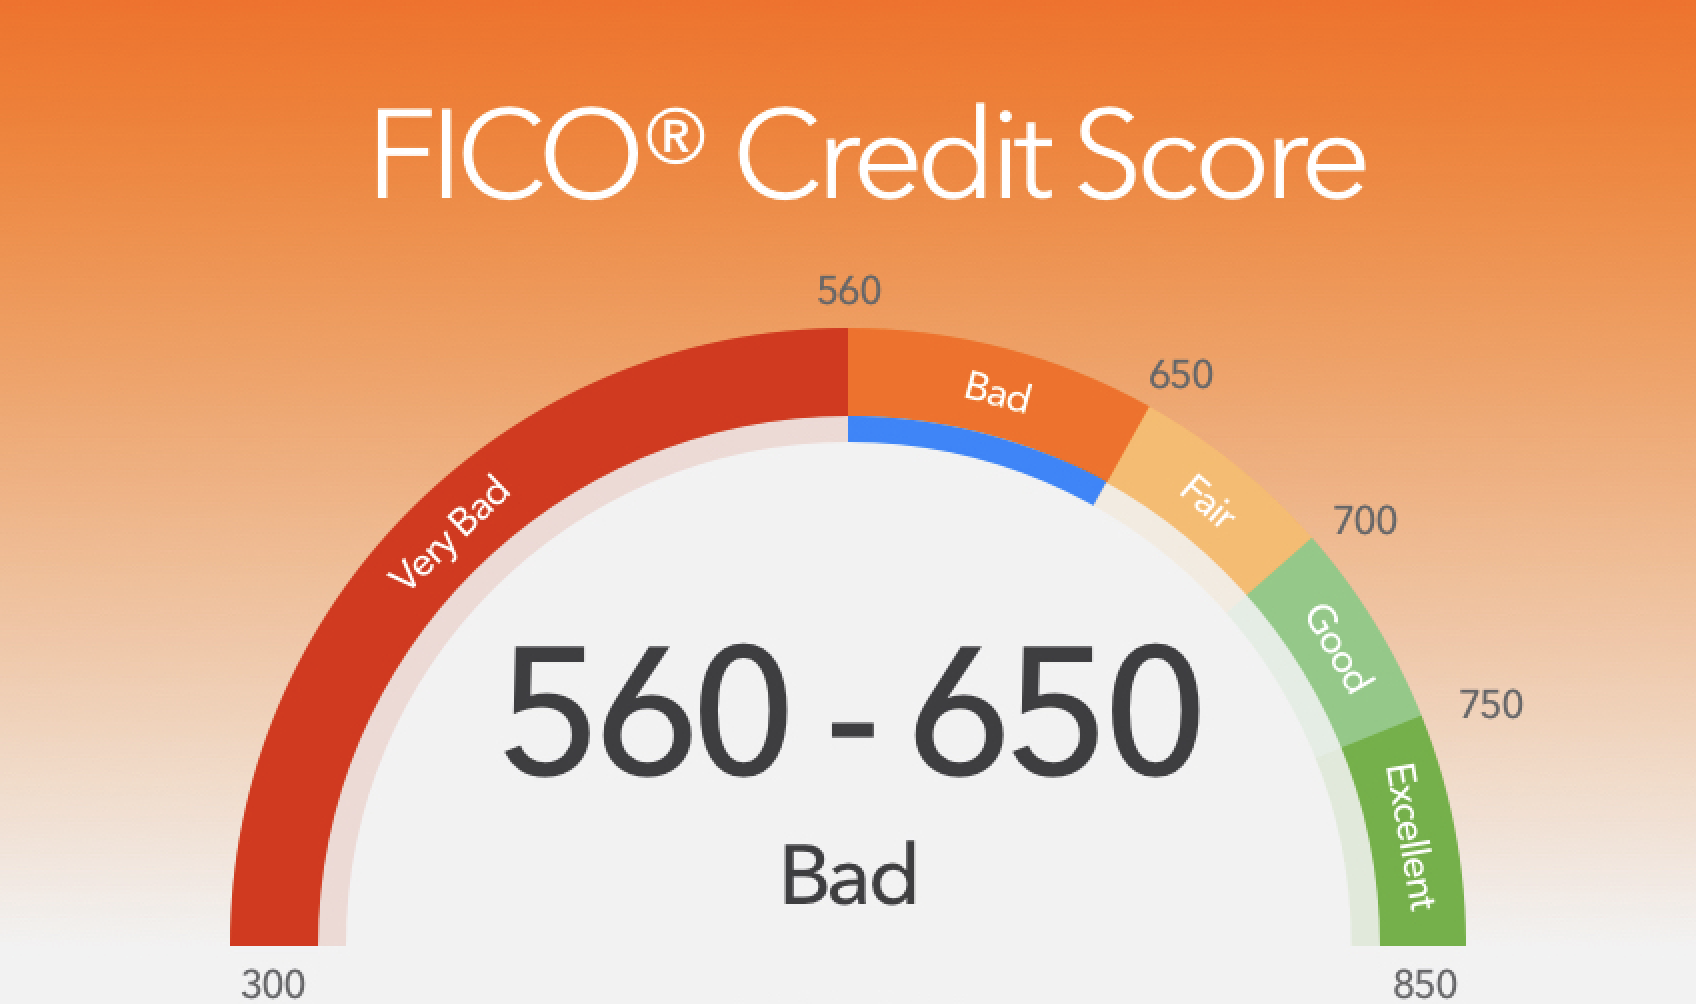
In recent years, the demand for emergency online payday loans has surged, notably for individuals with dangerous credit score. This development highlights a growing reliance on alternative lending options that always include exorbitant interest charges and hidden fees. In this article, we will explore the landscape of emergency online payday loans for those with poor credit score histories, analyzing their implications, accessibility, and potential pitfalls, as well as contemplating the broader financial context that drives people toward these loans.
The monetary world has evolved significantly with the appearance of the web. Conventional banking choices typically fall short for people with bad credit who might discover it challenging to secure loans via conventional means. Poor credit scores can result from various elements, together with earlier monetary struggles, unexpected medical bills, or inadequate credit histories. In these instances, emergency online payday loans present themselves as a quick fix for speedy cash stream points.
Emergency online payday loans are usually small, short-term loans intended to cowl urgent bills reminiscent of medical bills, automotive repairs, or unexpected emergencies. The process is comparatively straightforward. Borrowers can apply online with minimal necessities, usually needing only proof of revenue and a checking account. The velocity at which lenders can disburse these loans is one of their primary appeals, particularly for these going through a financial emergency. Often, borrowers can obtain funds within hours of software approval, making it a tempting option when cash is required urgently.
Nevertheless, the accessibility of those loans is a double-edged sword. Whereas they might provide rapid relief, they're fraught with potential risks, especially for borrowers with dangerous credit. Predatory lending practices have become a significant concern throughout the payday loan trade. Many lenders goal vulnerable populations who're already financially stressed, and the high-interest charges related to these loans can lure borrowers in a cycle of debt.
The typical payday loan carries an APR that may exceed 400%. For someone already dealing with unhealthy credit score, these rates might be inconceivable to manage. A typical state of affairs involves a borrower taking out a payday loan to repay an present one, resulting in a snowball impact where debt accumulates over time. This cycle typically exacerbates the financial struggles borrowers are attempting to escape, leaving them in a precarious scenario.
Moreover, the lack of regulation in lots of areas allows for predatory practices to flourish. Some lenders could advertise low-interest rates however bury the precise prices inside the positive print or impose exorbitant charges for providers akin to loan renewals. Federal and state laws differ broadly, additional complicating borrowers' understanding of the complete implications of their loans. Because of this, monetary literacy becomes crucial for individuals searching for these loans; unfortunately, it is usually probably the most financially fragile who lack the required knowledge to make informed selections.
The societal implications of emergency online payday loans for people with bad credit are regarding. As extra folks turn to these high-interest loans, the cycle of poverty perpetuates itself. Financial stability is crucial for healthy individuals and communities, and dependence on emergency payday loans can severely hinder one's capability to construct a stable monetary foundation. Affected individuals may discover themselves unable to save for emergencies, spend money on training, or interact in meaningful economic participation.
One other side to contemplate is the emotional toll that reliance on payday loans can take. The stress of managing financial insecurity can lead to anxiety, depression, and a number of different mental health issues. Borrowers could really feel trapped, viewing these loans as their solely possibility, which may lead to despair and feelings of hopelessness. The stigma associated with bad credit can further isolate individuals, stopping them from seeking help or discussing their monetary points with buddies and family.
It is important to highlight potential alternatives to emergency online payday loans. Varied nonprofit organizations supply monetary counseling and assistance. Exploring options for budget administration, credit repair services, and community help can provide extra sustainable solutions. Moreover, some employers present applications that allow staff to entry earned wages ahead of payday, which can forestall financial shortfalls with out incurring excessive-curiosity loans.
In response to the prevailing issues surrounding payday loans, some states have introduced legislation to regulate the trade extra strictly. Cap limits on interest charges and charges, necessary disclosures, and expanded borrower protections have emerged as critical areas of focus. In case you have just about any issues relating to wherever along with how to employ Bget top companies, you possibly can e-mail us with our own page. Yet, the effectiveness of such rules remains a subject of debate, as the demand for quick financial options continues unabated.
In conclusion, while emergency online payday loans could represent a necessary outlet for people with unhealthy credit going through quick financial crises, they typically create more complications than they alleviate. The allure of quick money can lead to a cycle of debt that's challenging to flee, impacting the bodily, emotional, and financial properly-being of borrowers. Addressing these points necessitates a multifaceted strategy, combining training, regulation, and accessible financial alternate options to assist individuals regain a foothold on their monetary journeys and break free from the constraints imposed by predatory lending practices. As we replicate on this subject, it is evident that while some people may need fast monetary assistance, the long-time period implications warrant a reevaluation of how such loans fit into an individual's overall financial health.