

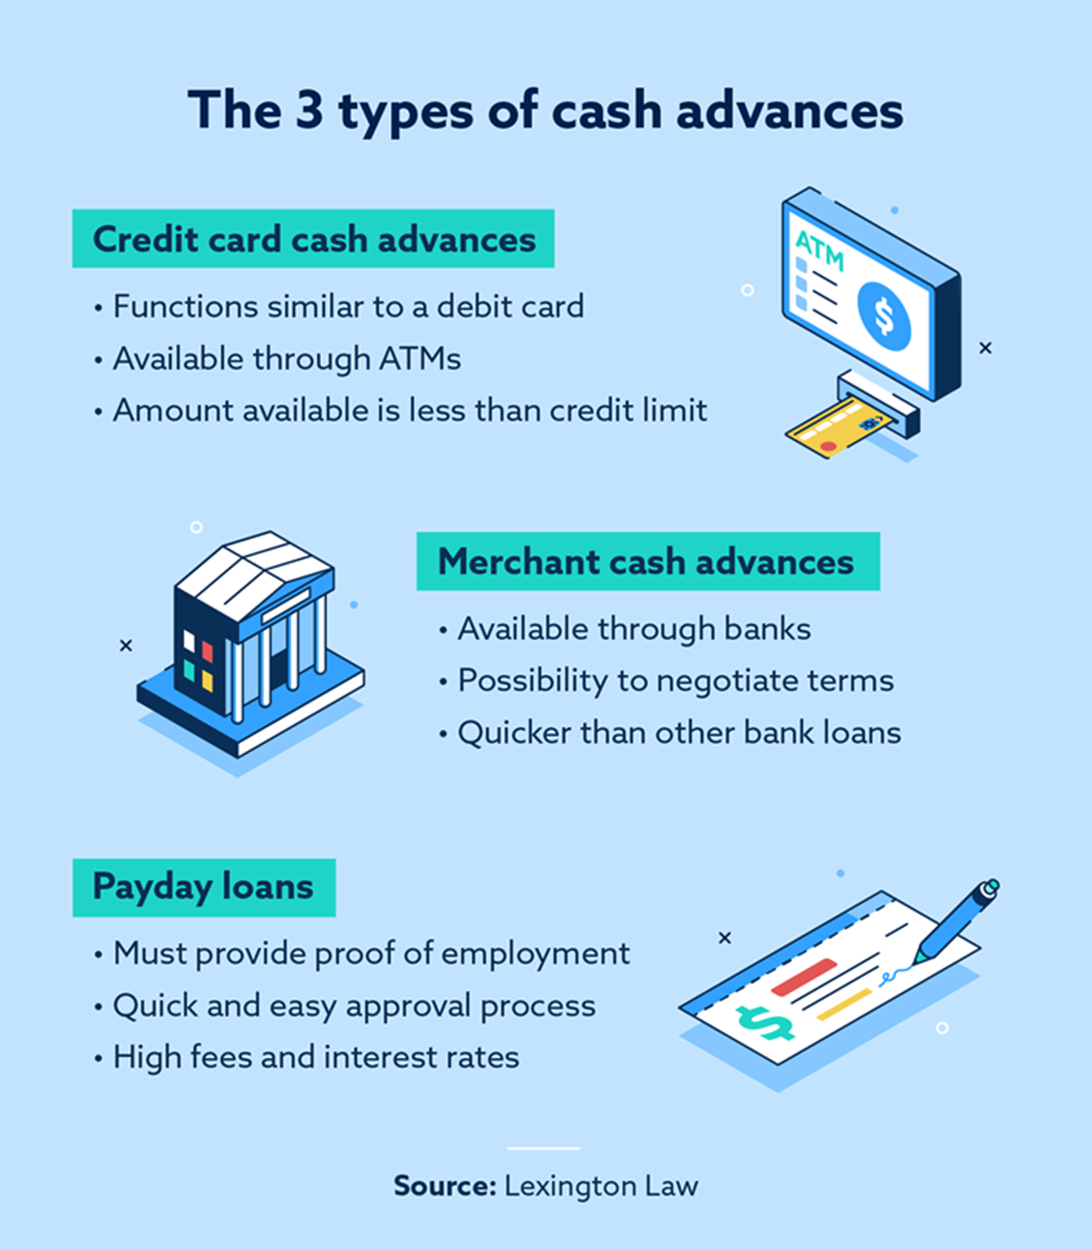
Payday loans have turn out to be a prevalent form of other financing, particularly among people dealing with financial shortfalls. Defined as small, quick-time period, unsecured loans sometimes due on the borrower’s subsequent payday, these loans goal shoppers in want of instant money to deal with emergencies or other financial calls for. Though payday loans current sure advantages, they also carry substantial dangers and implications for borrowers’ financial health. This article explores the mechanics of payday loans, their associated dangers, and viable alternate options that benefit consideration.
Mechanism of Payday Loans
Payday loans usually do not require extensive credit score checks, making them accessible to a broad section of the population. Borrowers usually provide a put up-dated examine or authorization for digital withdrawal as collateral. The loan amounts can vary from a number of hundred dollars to upwards of a thousand, depending on state regulations and lender insurance policies. Interest rates for payday loans might be notoriously high, usually exceeding 300% APR, which places them in a class of high-threat borrowing.
The strategy of obtaining a payday loan generally entails filling out a brief application, which might be accomplished online or in-particular person. Lenders require fundamental private information, proof of income, and generally a sound form of identification. Upon approval, borrowers receive funds nearly instantly. This immediacy is one in every of the first attracts of payday loans, as they will alleviate non permanent money stream issues without the prolonged processing times widespread in conventional banking.
Monetary Implications of Payday Loans
Regardless of their accessibility, payday loans can exacerbate financial difficulties for many borrowers. The high costs associated with these loans can trap people in a cycle of indebtedness. As a result of brief repayment terms — often just a few weeks — borrowers might battle to repay the loan on time. Because of this, many resort to rolling over the loan or taking out additional payday loans to cover the original debt, additional compounding their monetary burden.
A 2018 research printed within the Journal of Shopper Affairs highlighted that just about 70% of payday borrowers report taking out a number of loans inside a yr to manage existing debt. This cycle can lead to an insurmountable debt load, with borrowers repaying way over the initial loan quantity. Moreover, missed payments or failure to repay can lead to further charges, legal motion, and potential injury to the borrower’s credit rating.
The socioeconomic implications of payday loans are also important. Research indicates that communities with a excessive density of payday lending institutions usually correlate with decrease common incomes and poorer credit score rankings. This relationship underscores the predatory nature of payday loans, especially in marginalized demographics where access to traditional credit score is proscribed.
Regulatory Panorama
The regulatory atmosphere surrounding payday loans varies significantly across states and nations. In the United States, some states have imposed strict limits on payday lending operations, including caps on interest rates, most loan amounts, and the duration of repayment phrases. Conversely, in states with fewer restrictions, payday lending stays a profitable industry. The lack of federal rules has led to vast discrepancies in entry and protections for shoppers, prompting calls for reform.
Opponents of payday loans advocate for stricter laws, arguing that such measures would assist protect weak populations from predatory lending practices. Proponents argue that payday loans offer essential liquidity and financial flexibility, particularly for these with restricted credit choices. This ongoing debate highlights the necessity for balanced laws that protect customers whereas also permitting them entry to vital credit score assets.
Alternate options to Payday Loans
Given the pitfalls associated with payday loans, shoppers are inspired to discover various forms of financing that current lower dangers and costs. Some viable options embody:
- Credit Unions: Many credit score unions supply small personal loans and payday different loans (PALs) with considerably decrease curiosity rates and extra flexible repayment terms. These loans are designed to assist borrowers avoid the pitfalls of traditional payday loans.
- Personal Installment Loans: Not like payday loans, personal installment loans allow borrowers to repay the amount over a longer period. Typically, additionally they come with lower interest charges, making them a extra manageable choice for individuals needing cash.
- Employer Advances: Some employers offer wage advances or payroll advances to staff facing momentary financial difficulties. These advances enable staff to access earned wages before their regular pay date with out incurring excessive-curiosity costs.
- Budgeting and Emergency Funds: Constructing a private funds and financial savings for emergencies can scale back dependence on payday loans. Financial training applications usually emphasize the importance of saving for unforeseen expenses, which might mitigate the necessity for top-cost borrowing.
- Neighborhood Assistance Programs: Nonprofit organizations and government applications typically offer financial assistance to individuals in crisis. These programs present a safety internet for those who may in any other case resort to payday loans.
Payday loans can function a fast monetary fix for a lot of, but the potential lengthy-time period repercussions usually overshadow the immediate advantages. If you adored this article and you simply would like to collect more info pertaining to fulljam kindly visit our web-page. High-curiosity rates, collapsing into debt cycles, and the socioeconomic implications increase basic questions concerning the fairness and sustainability of this lending apply. As consciousness grows regarding the predatory nature of payday lending, it is crucial for shoppers to be knowledgeable about their options and the consequences associated with high-price borrowing. Education on effective monetary management and exploring viable alternatives are important in making a extra equitable monetary system that fosters larger shopper protection and financial well-being. By understanding the full landscape of payday loans and their impression, customers could make higher-informed financial selections that serve their lengthy-term pursuits.


