Miriam Chen, a 58-yr-outdated monetary analyst, stood at a crossroads as she approached retirement planning. Her Traditional IRA was invested primarily in a diversified mixture of stock mutual funds and bond funds, chosen for regular development and dependable earnings. But after several years of markets swaying with geopolitical information and inflation expectations rising, she found herself uneasy about how her retirement financial savings would carry out in a downturn. She had heard stories of treasured metals performing as a hedge throughout occasions of stress, and she started to surprise whether or not a portion of her IRA may very well be allocated to physical gold inside a self-directed association. The idea of a gold-backed retirement account appealed to her as a diversification technique, a possible safeguard towards equity danger, and a option to align her portfolio with a protracted-time interest in tangible assets.
Rationale and determination-making
Miriam’s first step was to separate what she hoped to perform from what she feared. Her targets have been simple: preserve purchasing power during inflationary periods, cut back correlation with traditional equities, and maintain liquidity enough to fund living bills once she retired. She was conscious of the costs and complexities associated with a Gold IRA, including setup fees, annual upkeep prices, and storage charges. Most importantly, she understood that simply "owning gold" in an everyday account doesn't qualify for tax-advantaged therapy inside an IRA; to maintain tax-deferred standing, the gold must reside in a custodian-permitted self-directed IRA with a licensed depository.
The plan she settled on was a direct rollover from her traditional IRA to a self-directed IRA that permitted physical valuable metals. The direct rollover logic was essential: shifting assets instantly from one custodian to a different avoids a taxable distribution, whereas an oblique rollover would require the owner to obtain the distribution, then redeposit into the new account inside 60 days—risking taxes and penalties if something went flawed. Miriam also decided on a moderate preliminary allocation to gold, with the expectation that the position would be rebalanced if market conditions or personal circumstances modified.
The mechanics of the rollover
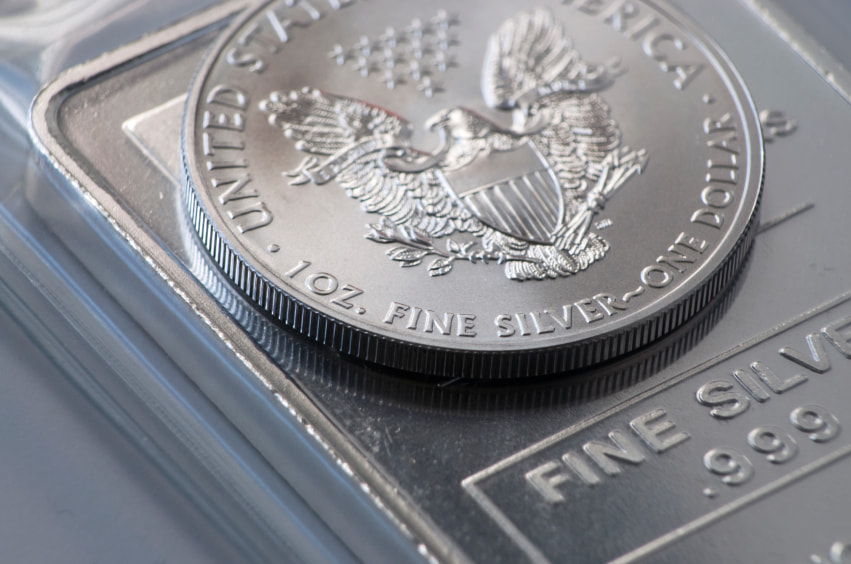
With skilled steerage, Miriam opened a self-directed IRA account via a custodian experienced in precious metals. The custodian explained two essential eligibility guidelines: the metals should be IRA-eligible, meaning they meet fineness and purity standards, and the items should be held by an accepted depository, not in a personal secure or residence. For gold, IRA-eligible choices usually embody certain coins and bars that meet minimal fineness requirements (typically round 99.5% or higher) and are minted by respected, IRS-authorised refiners. Common examples cited by custodians included broadly acknowledged coins such because the American Gold Eagle and Canadian Gold Maple Leaf, as well as excessive-purity gold bars from accepted refiners. Miriam noted these specifics, recognizing that not every gold product might be held in an IRA.
The actual rollover was arranged as a direct custodian-to-custodian transfer. Her former IRA custodian issued a switch request to the brand new metals custodian, which then coordinated with the vaulting facility to ensure the belongings could be deposited into the depository as a part of the IRA’s holdings. This step is critical for maintaining tax-advantaged status. The depository, a separate, insured facility, held physical gold in safe vaults, with the possession recorded in the IRA’s custodian records and the investor’s title listed as the beneficial proprietor on the IRA account.
Selecting storage and accountability
Storage selections are a defining function of a Gold IRA. Physical gold inside an IRA cannot be privately held; it resides with a depository chosen with the custodian’s steerage. The depository typically supplies insured storage, common audits, and online entry to the inventory, usually together with serially tracked coins or bars. Miriam’s selection process favored recognized, well-capitalized depositories with robust insurance protection and impartial audits. The custodian outlined ongoing annual storage charges and account upkeep prices, plus any transaction prices if she needed to liquidate or regulate allocations.
From a risk management perspective, Miriam was centered on transparency and liquidity. She requested for detailed statements that confirmed the weight, serial numbers, and present market values of each steel merchandise, together with the depository’s insurance coverage coverage and the process for initiating distributions. The depository’s consolation with segregation of assets—ensuring that her metals weren't commingled with different clients’ holdings—also mattered to her, as this supplied clarity for audits and potential future gross sales.
The portfolio consequence and performance
After the rollover, Miriam allocated roughly 20-25% of her IRA’s stability to physical gold throughout the self-directed account, with the remainder diversified into traditional assets, including cash-equivalents and bonds. The intention was to create a ballast that could dampen drawdowns in fairness markets whereas keeping liquidity to cover living expenses in retirement.
Over the next three years, the gold allocation acted as a hedge throughout durations of rising inflation and market volatility. When equities confronted pullbacks attributable to geopolitical tensions, the gold portion tended to carry its worth or respect, helping to mitigate general portfolio declines. The self-directed IRA construction allowed Miriam to avoid triggering a taxable occasion during the transition, preserving the tax-deferred standing of the funds as they continued to grow for retirement.
One in all the practical realities Miriam confronted was the commerce-off between liquidity and storage prices. The gold held within the IRA required periodic monitoring of spot prices and depository fees, and the reading of valuation statements may very well be much less intuitive than evaluating inventory mutual funds. When she wanted to adjust her allocation—say, to rebalance risk nearer to retirement—she relied on the custodian’s guidance to execute a sale inside the IRA, with proceeds directed again to cash or different eligible assets within the account. This process ensured compliance with IRS rules and averted any distribution that will incur taxes and penalties.
Tax, compliance, and regulatory concerns
A central lesson from Miriam’s case was the significance of compliance. The IRS permits rollovers to a self-directed IRA in a tax-advantaged manner only when the switch is executed as a direct rollover between establishments, not as a distribution to the beneficiary. She documented each step, from the preliminary decision to the final transfer, together with the rollover timing and the depository preparations. She additionally scheduled periodic critiques together with her tax advisor to ensure that the annual studies and required minimal distributions (RMDs) were dealt with accurately. The RMD panorama had developed in recent years; in Miriam’s situation, she was mindful that the IRA’s whole value—whether invested in traditional property or bodily metals—could decide her required distributions once she reached the related age.
One other regulatory nuance involved qualifying metals. Not all gold merchandise are eligible for an IRA. The gold held inside an IRA should come from permitted sources and meet minimum fineness requirements. If a non-qualifying merchandise entered the account, it could jeopardize the tax-advantaged standing of the IRA and trigger penalties. Miriam’s due diligence with respected custodians and dealers helped reduce this danger, guaranteeing that the gold in her portfolio remained compliant.
Lessons discovered and takeaways
From Miriam’s expertise, a number of pivotal takeaways emerged:
- Diversification issues: a measured allocation to gold can diversify threat and provide a hedge throughout inflationary cycles, but it surely needs to be a part of a broader, thoughtfully constructed retirement plan.
- The mechanics are important: a direct rollover minimizes tax danger and avoids accidental distributions. Working with reputable custodians and depositories is important for compliance and safety.
- Costs matter: ongoing storage and maintenance charges can erode returns if not monitored. A transparent charge structure helps traders understand the true price of ownership and plan accordingly.
- Eligibility and reliability: not all gold merchandise are eligible for IRAs. Investors should verify purities, minting, and eligibility with their custodian before buying.
- Liquidity and distribution: despite holding bodily gold within an IRA, liquidity for sunshinearticles withdrawals is primarily accessed via the IRA account. Investors ought to be ready to liquidate within the IRA framework quite than taking physical possession.